
Project Finance · Permanent Removal · 1 September 2026
Contract First, Capacity Second: How A 50,000 Tonne Namibia Biomass Storage Offtake Reprices Project Finance For Permanent Removal
Senken and Carbonsate’s 17 August 2026 announcement of a 50,000 tonne offtake for the Otjiwarongo biomass storage project in Namibia is a project-finance test, not a supply headline. The contract runs 2026 to 2028 against a project that has issued 799 tonnes on the Puro registry. The gap between contracted volume and operating base is exactly what a lender underwrites.
Thesis
Senken’s 17 August 2026 announcement of a 50,000 tonne offtake with Carbonsate for the Otjiwarongo biomass storage project in Namibia is a project-finance test, not simply a permanent-removal supply headline.1 The contract runs 2026 to 2028 against a project that has issued 799 tonnes on the Puro registry and is scheduled to deliver roughly 10,000 tonnes in 2026, with future capacity beyond 100,000 tonnes a year.1,3 The gap between contracted volume and operating base is the point. That gap is exactly what a lender underwrites, and it is what the market has to learn to price. Contract first, capacity second.
The Deal In Numbers
The offtake covers 50,000 tonnes of Puro.earth-certified permanent carbon removal, with credit vintages spanning 2026, 2027 and 2028. Senken procured the volumes on behalf of European corporate partners whose net-zero commitments carry near-term demand for verified removal. Adrian Wons, CEO of Senken, framed the multi-year lock-in as a way to secure access at prices European buyers can plan with. Johanna Broell, co-founder and CEO of Carbonsate, framed it from the developer side: long-term commitments give project developers the certainty to build ahead of demand.1
The project itself is Carbonsate Project Namibia, registered on the Puro registry as project 583695. Its methodology is Terrestrial Storage of Biomass, its durability label is CORC 100+, and its crediting period runs from 1 January 2025 through 31 December 2029. The registry currently records 799 issued credits from a single issuance dated 15 December 2025 and 323 credits retired against them.3
Financing Test, Not Supply Milestone
The natural read of a 50,000 tonne offtake in a market that has delivered roughly 1.5 million tonnes of permanent removal to date is that the deal expands supply meaningfully. It does. At 50,000 tonnes, the Senken-Carbonsate commitment is equivalent to about four percent of the delivered permanent-removal market.1 That is not the frame that matters for the reader who allocates capital.
The frame that matters is that Carbonsate is contracted for 50,000 tonnes over three years while its registry-verified operating base is 799 tonnes. The scheduled 2026 delivery is roughly 10,000 tonnes.1 The 50,000 tonne headline therefore requires the project to walk from a first-vintage cohort of hundreds of tonnes to a delivery cadence in the tens of thousands. That walk is a construction and commissioning question. It is a working-capital and ramp-up capex question. It is a verification-cycle question. It is, in short, a project-finance question.
Every one of those sub-questions has to be priced by whoever provides the financing that lets Carbonsate build the additional chambers ahead of delivery. A buyer commitment reduces one variable in that pricing exercise, revenue uncertainty. It does not reduce the others.
What Makes A Carbon Offtake Bankable For Project Finance?
A lender in project finance does not underwrite the headline tonne. A lender underwrites four moving parts, and each one has to hold on its own before the facility gets written. In a durable-removal offtake with a multi-year delivery schedule, those four parts are revenue, capacity, verification and security.
Revenue — the contracted delivery schedule sets the top line of the cashflow model, mapped tonne by tonne against each vintage year, because it is the schedule not the total that services debt. Senken has secured credit vintages by year across 2026, 2027 and 2028, which anchors the model.1
Capacity — the physical ramp-up from today’s operating base to the contracted forward volume is what the lender sizes the facility against, because unbuilt capacity is unbuilt revenue no matter what the offtake says. Additional sealed underground chambers, the harvesting operations that feed them and the monitoring sensors that certify them all sit ahead of delivery. Carbonsate has stated that the project can scale beyond 100,000 tonnes a year within the next few years.1 The financing question is how much of that ramp-up sits between 799 tonnes and 100,000 tonnes, and how much of it precedes revenue.
Verification — the lag between physical delivery and cashflow at retirement is timed by the registry certification cycle, and it forces the lender to size working capital and interest reserve around that gap. Each tonne is independently verified under the Puro.earth standard before a credit is issued. The 15 December 2025 issuance of 799 tonnes is the benchmark for cycle time between wood being sealed underground and a credit being available to deliver.2,3
Security — the recourse a lender draws on if the developer under-delivers is the piece most developers get wrong. It is not the registry buffer pool. The buffer pool sits at the system layer and gives the lender nothing. Security is a project-level holdback account, a substitute-credit obligation, a sponsor guarantee or delivery insurance. A 50,000 tonne contract with two thirds of its volume yet to be created has to carry one of these mechanisms sized against the downside case.
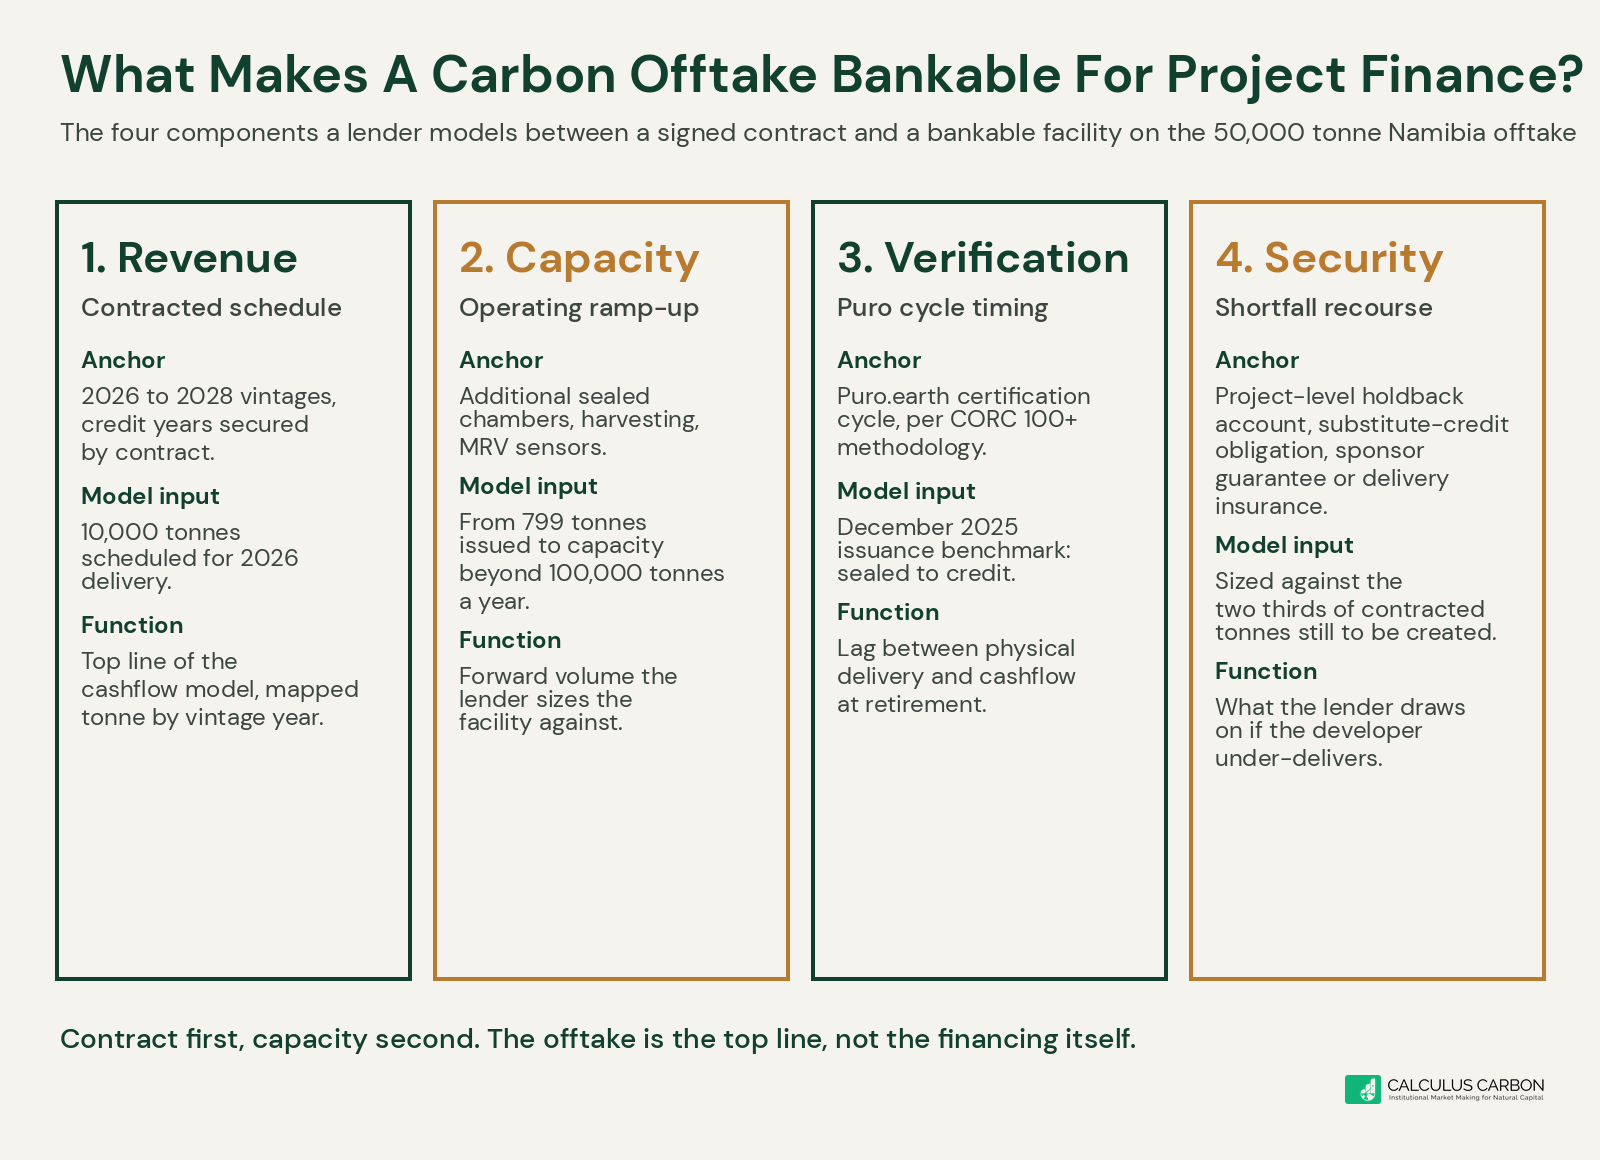
Once those four parts sit in one model with primary-source figures behind each row, the deal becomes financeable. The offtake alone is not financing. The offtake is the top line of the financing, and a gap on any one of the four blocks is a gap on the facility.
The Comparable
Mast Reforestation’s Montana biomass burial project, Mast Wood Preserve MT1, ran the same play in the same year. Its January 2026 issuance of 4,277 credits was the largest issuance to date under Puro.earth’s Terrestrial Storage of Biomass methodology and moved from excavation to issuance in nine months.4 Every credit sold in under six weeks, to a buyer group that included Bain & Company, BMO Financial Group, Royal Bank of Canada and CNaught.4
Mast’s read is instructive for two reasons. First, the buyer stack tells the market that the demand for durable removal in this pathway is not speculative. Corporate procurement, bank treasuries and structured buyers absorbed the entire issuance. Second, Mast has stated a longer-term deployment goal of 150,000 tonnes annually by 2030.4 That goal is a capacity ambition sitting behind a small operating base. The financing question that Mast has already answered on the demand side, Carbonsate is now testing on the delivery side. Sequencing matters. Contract first, capacity second, works only if the capacity plan is bankable.
Registry Context: Where This Sits
Puro.earth’s own numbers frame the market context. As of the July 2026 milestone announcement, the registry had issued more than 1.5 million CORCs, retired 1 million CORCs, and cleared 350 transactions across 53 projects in 20 countries in the first half of 2026 alone.5 Terrestrial Storage of Biomass accounted for 6,624 retired CORCs, roughly 0.7 percent of retired volume.5 Average time from issuance to retirement collapsed from 510 days in 2019 to 7.7 days in 2026, and average time to primary trade collapsed from 115 days in 2024 to 6.7 days in 2026.5
The compression of retirement lag matters for the underwriting model. Faster clearing between issuance and retirement reduces the working capital that a project developer needs to carry post-issuance. It shortens the lag between the tonne being verified and the tonne producing cashflow. A short primary-trade cycle also means that any credits Carbonsate issues under the multi-year offtake move to retirement without an inventory-financing overhang.5,6
Financeable, In Practical Terms
Reading Senken’s 50,000 tonne commitment through this lens produces a specific list of what a project-finance lender needs to see before writing a debt facility against the offtake. A base-case cashflow model with the 2026 delivery at approximately 10,000 tonnes, verification cycle time modelled off the December 2025 Carbonsate issuance, and the 2027 to 2028 volumes back-solved from Carbonsate’s stated capacity trajectory.1,3 A capex schedule for additional chambers and harvesting infrastructure that reconciles Carbonsate’s 100,000 tonne per year ceiling to the 50,000 tonne offtake window, with a construction-completion contingency.1 A verification and issuance timeline that maps each contracted vintage to a Puro certification cycle, using the December 2025 issuance date as the benchmark for cycle time.3 A security package sized against the two thirds of contracted tonnes still to be created, structured as one or more of a project-level holdback account, a substitute-credit obligation, a sponsor guarantee or third-party delivery insurance. The registry buffer pool is not part of this package. Downside cases tested against forced-delay scenarios in Namibian harvesting operations, regulatory delays in Puro or Isometric certification, and any dispute mechanism in the offtake itself.
Only once those five rows sit next to primary-source data on one page does the offtake convert from a headline into a financing document. That conversion is not automatic. It is the work.
Namibia Adds A Layer, Not A Discount
Namibia’s arid climate and its 30 million hectares of encroacher-bush-affected farmland create the physical conditions for the project.1,2 The country’s political stability and the operational relationships with the Namibian Ministry of Agriculture and the German Society for International Cooperation give the project a workable institutional footprint.2 None of that makes Namibia risk-free for a lender. It means the lender needs to price sovereign delivery risk, currency exposure and host-country regulatory continuity into the model. It also means Carbonsate has already done the local-institutional work that many first-of-kind CDR projects have not.
Namibia is not a discount on the financing spread. It is a factor that has to be priced explicitly rather than assumed away.
The Read for Institutional Capital
For an allocator or a corporate treasury tracking permanent removal, the practical takeaway is that a multi-year offtake against a small-issuance developer is not evidence of scale. It is a bridge that has to be modelled. The 50,000 tonne Senken-Carbonsate agreement is well-structured evidence that European buyers with CFO-level residual-emissions accountability are willing to commit ahead of capacity. That is one leg of a project-finance structure. The other leg, the capital that lets the developer build the capacity ahead of delivery, still has to be provided.
The next test is whether specialised project-finance providers can build the debt or hybrid facilities that let developers convert those offtakes into construction. When those facilities become standardised for durable-removal projects, the offtake will start behaving like an infrastructure contract. Until then, it behaves like a forward, and forwards without financing sit on developer balance sheets.
Contract first, capacity second, is the frame. A 50,000 tonne offtake is the top line of a financing, not the financing itself. The underwriting bridge is the work.
This piece pairs with a Neelesh Agrawal LinkedIn short-form scheduled for W36.
Sources
- [1] Senken, Senken and Carbonsate sign Europe’s largest biomass storage deal: 50,000 tonnes of permanent carbon removal, 17 August 2026. senken.io
- [2] Carbonsate, Namibia: The Otjiwarongo Project. carbonsate.com
- [3] Puro.earth Registry, Carbonsate Project Namibia (Project ID 583695). registry.puro.earth
- [4] Carbon Herald, Mast Reforestation sells out Montana biomass burial credits within weeks from issuance, January 2026. carbonherald.com
- [5] Puro.earth press release via Nasdaq, 1 million CORCs retired in Puro Registry, July 2026. nasdaq.com
- [6] Puro.earth, Puro Issuance Plus launch to enable higher-frequency carbon credit issuance for suppliers, January 2026. puro.earth